The short answer
What is the purpose of estate planning?
Estate planning exists to carry out your intentions when you can no longer carry them out yourself. A complete plan names who inherits and when, who makes financial and medical decisions if you are incapacitated, who raises your minor children, and how your assets pass without court delay, public exposure, avoidable tax or family conflict. The documents are the means. Those outcomes are the purpose.
- Only 24 percent of adults in a 2025 national survey reported having a will.[1]
- In Arizona, a will generally must be probated before it can transfer property;[2] a funded trust avoids that step.
- The 2026 federal estate, gift and GST exemption is $15 million per person, with a top rate of 40 percent above it.[3, 4]
- Arizona imposes no estate, inheritance or gift tax.[5]
Most people think of estate planning as paperwork for the end of life. In practice, the documents do much of their work while you are alive: when a surgeon needs a decision, when a bank needs a signature, when a company needs someone with authority. This guide explains what an estate plan is for, how Arizona law shapes it, and how its purpose grows as a family's wealth and complexity grow. It is written for households across Scottsdale, North Scottsdale, Paradise Valley and Carefree, and for the advisors who work alongside them.
What an estate plan is for
The purpose of estate planning is control, continuity and protection. Control means your choices govern, not a statute's defaults. Continuity means someone you trust can act the moment you cannot, without waiting for a judge. Protection means what you leave reaches the people you intend, in the form you intend, with as little lost to tax, creditors and conflict as the law allows.
Only 24 percent of adults surveyed by Caring.com in 2025 said they had a will, and 43 percent of those without one said they simply had not gotten around to it.[1] The gap matters because every family has a plan whether or not it writes one. Families who do not write their own inherit the one the legislature wrote for everyone.
While you are living
You keep control. A revocable trust holds your assets, you serve as trustee, and titles and beneficiary designations are coordinated with it.
If you cannot act
People you chose step in. Your financial agent, your health care agent and your successor trustee act without a court.
At death
Your instructions govern. The trust distributes privately, a pour-over will catches stray assets, and the guardians you named care for minor children.
For the generations after
Protection continues. Lifetime trusts, dynasty planning and family governance carry your intentions past the first inheritance.
Nine purposes of a complete estate plan
A complete estate plan serves nine purposes. Smaller estates lean most on the first four. Larger and more complex estates need all nine.
Decide who inherits, how much and when
Without a will or trust, Arizona's intestacy statutes choose your heirs, and the result often surprises families. If you are married and have a child from an earlier relationship, your surviving spouse receives one-half of your separate property and none of your half of the community property; the rest passes to your descendants.[6, 7] An unmarried partner receives nothing. A plan replaces those defaults with your own choices, and it also controls timing. A revocable living trust can hold a child's share until a sensible age, release it in stages, or keep it in trust for life.
Keep your family out of probate court
A will does not avoid probate. In Arizona a will generally must be accepted in probate before it can transfer property,[2] and creditors alone have four months from the first published notice to present their claims;[8] in our experience an Arizona probate commonly takes six to twelve months. The state offers shortcuts for small estates: thirty days after death, an affidavit can collect up to $200,000 of personal property, and no sooner than six months after death, an affidavit can transfer up to $300,000 of Arizona real property, each net of liens.[9] A beneficiary deed recorded before death can transfer a home.[10] For most households with a house and investment accounts, the dependable route is a funded revocable trust, which lets a successor trustee act the day it is needed. Our guide to revocable trusts after the 2025 tax law covers the mechanics, and our trust administration practice guides trustees through what comes next.
Name who decides if you cannot
This is the part of estate planning that works while you are alive. Without a durable power of attorney, your family must petition the court for a conservator, and for an adult the court must find by clear and convincing evidence, among other things, that you cannot manage your affairs effectively.[11] Personal and medical decisions can require a separate guardianship.[12] Arizona requires a financial power of attorney to be signed, witnessed by someone other than the agent, the agent's spouse or children, or the notary, and acknowledged before a notary.[13] A health care power of attorney and a living will name who speaks for you and record the care you want.[14, 15] These documents are central for clients planning in retirement, and they matter at every age.
Protect minor children and anyone who depends on you
A parent may appoint a guardian for a minor child by will.[16] Money is a separate question. A minor cannot manage an inheritance, so without a trust the court may appoint a conservator to manage it,[11] and when the conservatorship ends at adulthood the property generally passes to the child outright.[17] A trust lets you choose who manages the money, how it may be used and when your child takes control. Our article on children's trusts for lifetime planning covers lifetime trust options after the 2025 federal changes.
Reduce estate, gift and income taxes
For 2026 the federal estate, gift and generation-skipping transfer exemption is $15 million per person, set by the 2025 tax act with inflation adjustments beginning in 2027, and transfers above it are taxed at a top rate of 40 percent.[3, 18, 19, 4] Arizona adds no estate, inheritance or gift tax.[5, 20] A married couple can shelter $30 million, but only with planning. The unused exemption of the first spouse to die passes to the survivor only if an estate tax return makes the portability election, which the IRS allows up to five years after death for estates not otherwise required to file.[21, 22] The generation-skipping exemption is tied to the basic exclusion amount alone, so a deceased spouse's unused GST exemption does not pass to the survivor.[23, 21] Life insurance you own counts toward your estate,[24] which puts more families near the line than expect to be.
Income tax is the other half. Assets included in your estate generally take a new basis at death, and appreciated community property can take it on both halves at the first death.[25] Lifetime gifts help as well: in 2026 you can give $19,000 to each of any number of people, and pay tuition or medical bills directly for anyone, without touching the exemption.[3, 26] For estates near or above the exemption, lifetime tools such as spousal lifetime access trusts, dynasty trusts and irrevocable life insurance trusts move future growth outside the taxable estate. Our high net worth estate planning page and our analysis of the $15 million exemption explain where each fits.
Protect heirs from divorce, lawsuits and creditors
An inheritance left outright belongs to the heir, and to the heir's creditors. An inheritance left in a properly drafted trust is different: Arizona enforces spendthrift provisions, which generally keep a beneficiary's creditors from reaching trust assets before distribution.[27] Holding an inheritance in trust also helps keep it separate property, since Arizona treats property a spouse acquires by gift or inheritance as that spouse's separate property.[28, 29] Two limits are worth knowing. Your own revocable trust does not protect you from your own creditors,[30] and protection drawn too tightly can smother the people it is meant to help. Our irrevocable trust work aims for protection without governing from the grave.
Keep the business running
For many business owners the company is the estate. The plan has to say who can vote the shares, sign the checks and run the company the week after an owner dies or becomes incapacitated, and it has to agree with the operating agreement or buy-sell agreement. Owners approaching a sale have a narrower window: pre-sale trust and gifting strategy and qualified small business stock planning work best before a buyer is at the table, and a beneficiary defective inheritor's trust can keep a family member's high-growth business interest outside that person's taxable estate. For companies whose owners are also private clients, we serve as outside general counsel.
Support the causes you care about
Charitable planning makes philanthropy part of the plan rather than an afterthought. Donor-advised funds, charitable remainder and lead trusts, private foundations and qualified charitable distributions from IRAs each carry different tax results and different levels of family involvement. Principals of a family office can use charitable vehicles to bring the next generation into shared decisions.
Prevent disputes and pass on more than money
Estate disputes often begin with ambiguity: unclear documents, surprised heirs, a trustee nobody trusts. A good plan chooses fiduciaries deliberately, explains its reasoning where that helps, and anticipates the questions a trustee will face. Arizona's default rule requires trustees to keep qualified beneficiaries reasonably informed,[31] so a plan should be built to be administered in the open. It should also reach digital accounts: Arizona lets you authorize a fiduciary's access to your digital assets, including the content of messages, in a will, trust or power of attorney, unless an account's online tool records a different choice.[32] For multi-generational families, family meetings and written statements of intent often matter as much as the tax design.
What Arizona law does when there is no plan
The clearest way to see the purpose of a plan is to see the default it replaces.
| Situation | Without a plan | With a complete plan |
|---|---|---|
| You die married, and all of your children are also your spouse's | Your spouse takes the entire intestate estate, outright.[6] | You decide the shares, and a trust can protect your spouse and preserve the remainder for your children. |
| You die married, with a child from an earlier relationship | Your spouse receives one-half of your separate property and none of your half of the community property; the rest passes to your descendants.[6, 7] | You provide for your spouse and your children in the proportions and on the terms you choose. |
| You die unmarried with no children | Your estate passes to your parents, then to your siblings and their descendants. An unmarried partner receives nothing.[7] | A partner, friends, godchildren or charities inherit as you direct. |
| You become incapacitated | Your family petitions the court for a conservator and, if needed, a guardian,[11, 12] and the conservator must account to the court.[33] | The agents and successor trustee you named act at once, privately. |
| A minor child inherits | A court may appoint a conservator to manage the money,[11] and the child generally receives it outright when the conservatorship ends at adulthood.[17] | A trustee you chose manages the money for as long as you specify. |
| Your Arizona home passes | Probate, unless the property qualifies for the $300,000 affidavit, which cannot be used until six months after death.[9] | A funded trust transfers it without probate, as does a beneficiary deed recorded before death.[10] |
Simplified summary of Arizona statutes for illustration. Outcomes depend on how each asset is titled and on any beneficiary designations.
The four hallmarks of a complete plan
A hallmark is struck into precious metal to certify its standard. These four are ours, and every plan we draw carries all four.
-
Wills & Trusts
Instruments that keep a family out of probate court and its affairs private.
- Revocable living trusts and pour-over wills
- Irrevocable trusts: SLATs, dynasty and asset protection
- Special needs and supplemental needs trusts
- Trust funding and successor trustee counseling
-
Healthcare Directives
Decision makers you trust, able to act the moment they are needed.
- Durable health care powers of attorney
- Living wills and end of life directives
- HIPAA authorizations and mental health powers
- Coordination with physicians and care facilities
-
Wealth Transfer Tax Planning
Strategies that reduce estate, gift and generation-skipping transfer taxes.
- Grantor retained annuity trusts and grantor trust sales
- Family limited partnerships and LLCs
- Intra-family loans and lifetime gifting programs
- Dynasty and generation-skipping trust design
-
Charitable Planning
Philanthropy aligned with tax efficiency and family values.
- Donor-advised funds
- Charitable remainder and lead trusts
- Private foundations and supporting organizations
- Qualified charitable distributions from IRAs
Arizona rules that shape every plan
A plan drafted from a national template misses the features that make Arizona different. These are the ones we plan around most often.
- Community property
Property acquired during marriage is generally community property,[28] each spouse's one-half share passes under that spouse's own plan at death,[34, 6] and both halves can receive a basis step-up at the first death.[25]
- No state death taxes
Arizona repealed its estate tax in 2006, has imposed none for deaths after 2004, and has no inheritance or gift tax.[20, 5]
- Small estate limits
Up to $200,000 of personal property (after thirty days) and $300,000 of Arizona real property (after six months), each net of liens, can pass by affidavit.[9]
- Beneficiary deeds
Valid only if recorded before the owner's death, and able to name the trustee of a trust as the beneficiary.[10]
- Long-lived trusts
Arizona's rule against perpetuities generally allows an interest to vest or end as late as 500 years after it is created, which makes the state a strong home for dynasty trusts.[35]
- Decanting
A trustee with distribution discretion can often move assets to a new, better-drafted trust without court approval.[36] See trust planning and modification.
- Plans from other states
A will or trust validly made under the law of the place where it was signed or where you lived is generally valid here,[37, 38] but validity is not the same as fit with Arizona law.
How the purpose shifts as life and wealth change
The nine purposes stay constant. Which one leads depends on where you are.
| If you are | The plan's first job | Read next |
|---|---|---|
| Raising young children | Name guardians and hold any inheritance in trust | Children's trusts |
| A business owner | Keep the company running and align the plan with the operating or buy-sell agreement | Business owners |
| A senior executive | Plan around equity compensation, concentrated stock and deferred pay | Senior executives |
| Preparing to sell a company | Move future value out of the estate and plan qualified small business stock before closing | Business exits and liquidity events |
| Retired or nearing retirement | Incapacity documents, retirement accounts and a deliberate transfer to the next generation | Planning in retirement |
| Building wealth meant to last | Dynasty and generation-skipping planning with family governance | Multi-generational families |
| A family office principal | Independent counsel for trusts, entities and philanthropy | Family offices |
| An athlete or public figure | Privacy, entity structure and a plan built for a short, high-earning career | Athletes and public figures |
| Near or above $15 million | Use the exemption with SLATs, dynasty trusts and life insurance trusts | High net worth planning |
| A CPA or financial advisor | Coordinate the legal plan with your client's financial plan | For financial advisors |
See every client situation we serve on our who we serve page.
Ten differences, side by side
A plan serves its purpose only if the documents work when they are needed. These ten differences separate a plan built to work from a plan built to be signed.
01Advanced expertise and credentials
Boland Law Group
Every attorney holds a post-doctoral LL.M. in tax or estate planning in addition to the J.D., so plans are designed by specialists in tax and trust law.
Other firms
Many plans are drafted by general practitioners who also handle unrelated matters and have no graduate training in tax or trusts.
02Fully customized solutions
Boland Law Group
Documents are drafted for one family's assets, relationships and goals. Nothing is a fill-in-the-blank form.
Other firms
Standardized templates are reused from client to client, leaving gaps that surface only when the documents are needed.
03Consistently updated intellectual property
Boland Law Group
Our documents are reviewed and refined as statutes, regulations and court decisions change.
Other firms
Forms can go years without revision and carry outdated tax provisions into new plans.
04Direct attorney involvement
Boland Law Group
A partner handles the matter personally, from the first meeting through the signing.
Other firms
Drafting and client contact are often delegated to paralegals and staff, with limited attorney review.
05Premium, proactive service
Boland Law Group
We deliberately limit the number of engagements we accept, so each receives unhurried attention and follow-up.
Other firms
High-volume practices compete on speed and price, which leaves little time to find planning opportunities.
06Integrated business and financial insight
Boland Law Group
Attorneys with business, banking and tax backgrounds plan the company and the family as one plan.
Other firms
Estate documents are drafted without regard to the entity structure, buy-sell terms or liquidity needs of a family business.
07A comprehensive, long-term relationship
Boland Law Group
The plan is maintained as the family, the assets and the law change.
Other firms
The relationship ends at signing, and the plan ages quietly in a drawer.
08Confidentiality and trust
Boland Law Group
Sensitive family and financial details are handled directly by the attorneys.
Other firms
More hands on a file mean more chances for error and for disclosure.
09Protection from divorce, lawsuits and creditors
Boland Law Group
Trust design uses spendthrift terms, discretionary standards and careful titling to keep inheritances protected.[27]
Other firms
Outright distributions leave an inheritance exposed to a child's creditors and to divorce.
10Preservation without over-restriction
Boland Law Group
Plans protect family wealth without governing from the grave, so heirs keep real autonomy.
Other firms
One-size documents tend to fail in one of two directions: too restrictive, or too little protection.
The credentials behind these claims are documented on our quiet credentials page.
How a plan comes to be
Every engagement follows the same five steps, and the attorneys handle each one personally.
- A conversation. Call the office. We listen first: the family, the holdings, the intent.
- The invitation. If we are the right counsel, our planning questionnaire follows by private invitation.
- The design. Your attorney drafts a plan built for one family: yours.
- The review. Drafts in hand, we walk through the plan together, line by line, until it says exactly what you intend.
- The execution meeting. Signatures witnessed, trusts funded, and your advisors aligned around one strategy.
No engagement is formed until a written engagement letter is signed. To begin, request a consultation or call (480) 420-8268.
Where we meet clients
Our office is in the Scottsdale Airpark at 15100 N. 78th Way, Suite 203, Scottsdale, Arizona 85260. It is open Monday through Thursday from 9 a.m. to 5 p.m. Arizona time and on Saturdays by appointment, and every visit is by appointment. See all locations and appointment options.
- Scottsdale
Within about 25 minutes of most of the city.
- North Scottsdale
About 12 minutes to DC Ranch and Silverleaf, about 32 minutes to Desert Mountain.
- Paradise Valley
About 17 minutes, off-peak, from the center of town.
- Carefree
About 29 minutes from the Carefree Sundial, and serving Cave Creek.
- In your home
Across the East Valley, and in Prescott, Prescott Valley, Sedona, Clarkdale and Jerome.
- Anywhere in Arizona
Secure video and telephone consultations.
When to revisit the purpose of your plan
A plan is written for a family at a moment in time. Revisit it when the family, the assets or the law move.
- Marriage, divorce or a new partner. Arizona revokes many provisions for a former spouse on divorce,[39] but federal law can override that rule for employer benefit plans governed by ERISA,[40] so change those beneficiary forms directly.
- A birth, adoption or death, including the death or incapacity of anyone you named as trustee, agent or guardian.
- A move to Arizona. Caring.com's 2025 study reported that about 1 in 10 Americans no longer live in the state where they created their estate plan.[1]
- Property in another state, which can require a second probate unless it is titled to your trust.
- A business formation, sale or liquidity event.
- Net worth approaching the exemption, or a change in tax law such as the 2025 act.[18]
- Time. A review every three to five years is sound practice even when nothing obvious has changed.
Minor changes are made by amendment and structural changes by restatement. Irrevocable trusts can often be modernized too, through trust planning and modification.
Frequently asked questions
What is the main purpose of estate planning?
The main purpose of estate planning is to make sure your own decisions, not a court's or a statute's, govern what happens to you and to your property. A complete plan names who inherits and on what terms, who manages your finances and medical care if you cannot, who raises your minor children, and how assets pass privately and efficiently. Reducing taxes, protecting heirs, continuing a family business and supporting charities are purposes too, and they grow in importance as an estate grows.
Do I need an estate plan if my estate is below the $15 million federal exemption?
Yes. Most of what an estate plan does has nothing to do with estate tax. Families well below the exemption still need powers of attorney to avoid a court conservatorship, a guardian nomination for minor children, and a funded trust to keep an Arizona home and accounts out of probate. Income tax planning matters at every level, because the basis adjustment at death can eliminate built-in capital gain on appreciated assets. The exemption is also set by Congress, so a sound plan is built to adapt if it changes.
What happens if I die without a will in Arizona?
Arizona's intestacy statutes decide who inherits. If you are married and all of your children are also your spouse's children, your spouse takes your entire intestate estate. If you have a child from another relationship, your spouse receives one-half of your separate property and none of your half of the community property, and the rest passes to your descendants. An unmarried partner receives nothing. A court appoints the personal representative, and a minor heir's share may be managed under court supervision until adulthood.
Does a will avoid probate in Arizona?
No. A will directs how assets pass through probate; it does not keep them out of it. Arizona avoids probate for small estates by affidavit: thirty days after death for up to $200,000 of personal property, and no sooner than six months after death for up to $300,000 of Arizona real property, each net of liens. Assets with beneficiary designations, real estate covered by a beneficiary deed recorded before death, and anything titled to a funded revocable trust also pass outside probate. For most families with a home and investment accounts, the funded trust is the dependable route.
What is the difference between a will and a revocable living trust?
A will takes effect only at death and only through the probate court. A revocable living trust works as soon as you sign and fund it: you serve as trustee and keep full control, and if you become incapacitated or die, the successor trustee you chose steps in without a court. A trust can also hold an inheritance for years under instructions you write. Most Arizona plans pair the trust with a pour-over will that catches anything left outside it.
What documents are in a complete Arizona estate plan?
At minimum: a revocable living trust, a pour-over will, a durable financial power of attorney, a health care power of attorney, a living will and HIPAA authorizations. Most plans also include guardian nominations for minor children, coordinated beneficiary designations, deeds transferring real estate to the trust and, for married couples, careful treatment of community property. Larger estates add irrevocable trusts such as SLATs, dynasty trusts and life insurance trusts, business succession documents and charitable vehicles.
What happens if I become incapacitated without powers of attorney in Arizona?
Your family must ask the superior court to appoint a conservator for your finances and, if needed, a guardian for personal and medical decisions. To appoint a conservator for an adult, the court must find by clear and convincing evidence, among other things, that you cannot manage your affairs effectively, and the process involves a petition, notice, a hearing and continuing court oversight. A durable power of attorney avoids it. In Arizona that document must be signed, witnessed by someone other than the agent, the agent's spouse or children, or the notary, and acknowledged before a notary.
Can an estate plan protect my children's inheritance from divorce and creditors?
Yes, if the inheritance stays in a properly drafted trust. Arizona enforces spendthrift provisions, so a beneficiary's creditors generally cannot reach trust assets before they are distributed, and assets held in trust are easier to keep separate from a child's marital property. What a plan cannot do is shield you from your own creditors through your own revocable trust, which Arizona law leaves reachable during your lifetime. The aim is real protection that still leaves your children real autonomy.
How does community property affect estate planning in Arizona?
Property acquired by either spouse during marriage in Arizona is generally community property, owned one-half by each. When the first spouse dies, federal tax law can give both halves of community property a new income tax basis, not just the deceased spouse's half. For appreciated real estate or securities, that can remove decades of gain before the survivor sells. Good planning preserves the community character of those assets, documents separate property, and uses trust terms that keep the full step-up available.
Does Arizona have an estate tax or inheritance tax?
No. Arizona imposes no estate tax, inheritance tax or gift tax. It has not collected estate tax for deaths after 2004, and the legislature repealed the estate tax statutes in 2006. Only the federal estate, gift and generation-skipping transfer taxes apply. For 2026 each person's federal exemption is $15 million, a married couple can shelter $30 million with proper planning, and transfers above the exemption are taxed at a top rate of 40 percent. Property you own in another state can still be exposed to that state's estate or inheritance tax.
How much can I give away in 2026 without paying gift tax?
You can give up to $19,000 to each of any number of people in 2026 without using any exemption, and a married couple can give $38,000 per recipient by electing to split gifts. Tuition paid directly to a school and medical expenses paid directly to a provider are excluded without limit. Gifts above the annual exclusion reduce your $15 million lifetime exemption but create no tax until it is used up. Lifetime gifts also move future growth out of your estate, which is why larger estates use them deliberately.
Is my out-of-state will or trust still valid after I move to Scottsdale?
A will or trust validly made under the law of the place where you signed it or where you lived is generally valid in Arizona. Validity is not the same as fit. Documents drafted for a common law state may mishandle Arizona community property, name fiduciaries who cannot easily serve here, or overlook Arizona tools such as beneficiary deeds, and powers of attorney and health care forms built for another state can slow things down when they are needed. Caring.com's 2025 study reported that about 1 in 10 Americans no longer live in the state where they created their estate plan. A review after a move is inexpensive insurance.
How often should I review my estate plan?
Review it every three to five years, and sooner after a marriage, divorce, birth or death in the family, a move to or from Arizona, a purchase of property in another state, a business sale, or a significant change in net worth or tax law. Arizona revokes many provisions for a former spouse automatically on divorce, but federal law can override that rule for employer benefit plans governed by ERISA, such as many 401(k) plans and group life insurance, so those beneficiary forms should be changed directly. See trust planning and modification for how existing plans are updated.
Is a beneficiary deed enough to keep my Arizona home out of probate?
For one Arizona property and a simple family, it can be. A beneficiary deed transfers the home at death without probate, but only if it was recorded before death. It does nothing if you become incapacitated, it cannot hold the property in trust for a young or vulnerable beneficiary, it can leave several heirs as co-owners, and it does not help with property in other states. It works best as a supplement to a funded trust, and an Arizona beneficiary deed can name the trustee of your trust as the beneficiary.
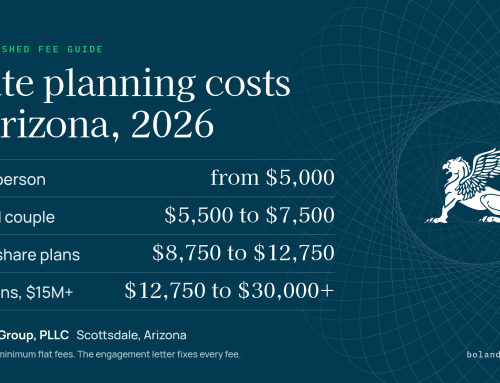
How much does estate planning cost in Arizona?
Cost depends on the size and complexity of the estate and on whether the work is a foundational plan or advanced tax planning. Boland Law Group publishes flat-fee schedules for core estate planning, tiered by the size of the gross estate, along with its hourly rates and billing practices, and its estimator gives a written range before the first meeting. Our 2026 guide to estate planning costs in Arizona compares pricing across the Phoenix and Scottsdale market and explains what drives it.
Who at Boland Law Group will draft my plan?
A partner. Both partners hold an LL.M., one in taxation and one in estate planning, and both are admitted to the Supreme Court of Arizona, the United States Tax Court and the United States District Court for the District of Arizona. A partner holding an LL.M. designs and drafts your plan and works with you from the first meeting through the signing. Nothing is handed to a document service, and we work alongside your CPA, financial advisor and insurance professional.
Do you meet clients outside Scottsdale?
Yes. Our office is in the Scottsdale Airpark at 15100 N. 78th Way, Suite 203, about 12 minutes from DC Ranch and Silverleaf, about 17 minutes from central Paradise Valley and about 29 minutes from the Carefree Sundial. We also see clients from Phoenix, Mesa and Cave Creek there, hold in-home appointments across the East Valley and in Prescott, Prescott Valley, Sedona, Clarkdale and Jerome, and meet by secure video or telephone. Every visit is by appointment.
Related reading
- Revocable trusts after the 2025 law: estate tax, basis step-up and wealth transfer
- Spousal lifetime access trusts: estate tax and basis planning
- Dynasty trusts: step-up in basis, estate tax changes and generational wealth
- BDITs and BDOTs in estate planning
- Estate tax update: the $15 million exemption, and why planning still matters
- Estate planning costs in Arizona, 2026
- QSBS trust stacking under Treasury scrutiny (2026)
- Tax controversy and litigation: the counsel who drafts a plan should be able to defend it.
Browse all estate planning articles, every insight or all six practice areas.
Sources
Numbered citations in the article link to the entries below. Statutes are linked to the Arizona Legislature and to the Legal Information Institute at Cornell Law School for convenience, and other sources link to their publishers; the official text controls.
- Victoria Lurie, 2025 Wills and Estate Planning Study, Caring.com (updated Sept. 17, 2025), survey of 2,500+ U.S. adults conducted with YouGov. caring.com. Back to text
- A.R.S. § 14-3102, Necessity of statement or order of probate for will; exception. azleg.gov. Back to text
- Internal Revenue Service, Rev. Proc. 2025-32 (released Oct. 9, 2025), § 2.14 (basic exclusion amount and GST exemption of $15,000,000 for 2026, adjusted for inflation beginning in 2027) and § 4.42 (annual exclusion of $19,000). irs.gov. Back to text
- 26 U.S.C. § 2001, Imposition and rate of tax; § 2001(c) sets the top rate at 40 percent. Cornell LII. Back to text
- Arizona Department of Revenue, Publication 900, Estate Tax (rev. Sept. 2006), stating that Arizona imposes no estate tax for decedents dying after 2004 and does not impose an inheritance or gift tax. azdor.gov. Back to text
- A.R.S. § 14-2102, Intestate share of surviving spouse. azleg.gov. Back to text
- A.R.S. § 14-2103, Heirs other than surviving spouse; share in estate. azleg.gov. Back to text
- A.R.S. § 14-3801, Notice to creditors (claims due within four months after first publication). azleg.gov. Back to text
- A.R.S. § 14-3971, Collection of personal property by affidavit; ownership of vehicles; affidavit of succession to real property. azleg.gov. Back to text
- A.R.S. § 33-405, Beneficiary deeds; recording; definitions. azleg.gov. Back to text
- A.R.S. § 14-5401, Protective proceedings; fingerprinting. azleg.gov. Back to text
- A.R.S. § 14-5303, Procedure for court appointment of a guardian of an alleged incapacitated person. azleg.gov. Back to text
- A.R.S. § 14-5501, Durable power of attorney; creation; validity. azleg.gov. Back to text
- A.R.S. § 36-3221, Health care power of attorney; scope; requirements; limitations; fiduciaries. azleg.gov. Back to text
- A.R.S. § 36-3261, Living will; verification; liability. azleg.gov. Back to text
- A.R.S. § 14-5202, Testamentary appointment of guardian of minor. azleg.gov. Back to text
- A.R.S. § 14-5430, Termination of proceeding (on termination, title passes to the formerly protected person). azleg.gov. Back to text
- Pub. L. No. 119-21, § 70106, 139 Stat. 72 (July 4, 2025) (H.R. 1, 119th Cong.), amending 26 U.S.C. § 2010(c)(3). congress.gov. Back to text
- Internal Revenue Service, IRS releases tax inflation adjustments for tax year 2026, including amendments from the One, Big, Beautiful Bill, IR-2025-103 (Oct. 9, 2025). irs.gov. Back to text
- Ariz. S.B. 1170, 47th Leg., 2d Reg. Sess. (2006), estate; generation skipping taxes; repeal, signed May 8, 2006 (Laws 2006, ch. 262); House summary. azleg.gov. Back to text
- 26 U.S.C. § 2010, Unified credit against estate tax; § 2010(c)(2), (4) and (5) define the applicable exclusion amount, the deceased spousal unused exclusion amount and the portability election. Cornell LII. Back to text
- Internal Revenue Service, Rev. Proc. 2022-32 (July 8, 2022), simplified method for a late portability election up to the fifth anniversary of death. irs.gov. Back to text
- 26 U.S.C. § 2631, GST exemption; § 2631(c) sets the exemption equal to the basic exclusion amount under § 2010(c). Cornell LII. Back to text
- 26 U.S.C. § 2042, Proceeds of life insurance. Cornell LII. Back to text
- 26 U.S.C. § 1014, Basis of property acquired from a decedent; see § 1014(b)(6) for community property. Cornell LII. Back to text
- 26 U.S.C. § 2503, Taxable gifts, including § 2503(b) (annual exclusion) and § 2503(e) (tuition and medical payments). Cornell LII. Back to text
- A.R.S. § 14-10502, Spendthrift provision. azleg.gov. Back to text
- A.R.S. § 25-211, Property acquired during marriage as community property; exceptions; effect of service of a petition. azleg.gov. Back to text
- A.R.S. § 25-213, Separate property. azleg.gov. Back to text
- A.R.S. § 14-10505, Creditor's claim against settlor. azleg.gov. Back to text
- A.R.S. § 14-10813, Duty to inform and report. azleg.gov. Back to text
- A.R.S. § 14-13104, User direction for disclosure of digital assets, part of Arizona's Revised Uniform Fiduciary Access to Digital Assets Act (A.R.S. § 14-13101 and following). azleg.gov. Back to text
- A.R.S. § 14-5419, Accounts; definition. azleg.gov. Back to text
- A.R.S. § 14-3101, Devolution of estate at death; administration on deaths of husband and wife. azleg.gov. Back to text
- A.R.S. § 14-2901, Nonvested property interest; general power of appointment; validity; exception (the 500-year period is in subsection A, paragraph 2). azleg.gov. Back to text
- A.R.S. § 14-10819, Trustee's special power to appoint to other trust. azleg.gov. Back to text
- A.R.S. § 14-2506, Execution; choice of law. azleg.gov. Back to text
- A.R.S. § 14-10403, Trusts created in other jurisdictions. azleg.gov. Back to text
- A.R.S. § 14-2804, Termination of marriage; effect; revocation of probate and nonprobate transfers; federal law; definitions. azleg.gov. Back to text
- Egelhoff v. Egelhoff, 532 U.S. 141 (2001) (ERISA preempts a state statute that revoked a former spouse's beneficiary designation, as applied to an employer's ERISA-governed life insurance and pension plans). Cornell LII. Back to text
Important legal notice
Please read this notice before relying on anything in this article. By reading this article you acknowledge the following.
Information only, not advice
This article is general educational information about federal and Arizona law and estate planning. It is not legal, tax, accounting, investment, or financial advice, and it is not a substitute for advice from a qualified professional who knows your facts. Do not act, or refrain from acting, based on anything in it.
No attorney-client relationship
Reading this article, using this website, calling, emailing, or submitting a form does not create an attorney-client relationship with Boland Law Group, PLLC or any of its attorneys. A relationship is formed only after a conflict check, a written engagement letter signed by the client and the firm, and payment of any required fees, as described in our Terms of Engagement. Until then, please do not send confidential information; anything you send may not be treated as privileged or confidential.
Not a tax opinion; not for penalty protection
This article is not a tax opinion or written tax advice on which any person may rely. It was not written to be used, and cannot be used, by any person to avoid penalties that may be imposed under the Internal Revenue Code or any state or local tax law. It is not an offer, solicitation, promotion, or recommendation of any transaction, investment, trust structure, or tax strategy.
No guarantee of any outcome
No result is promised or guaranteed. Courts, the Internal Revenue Service and state agencies may disagree with any view expressed here. Whether any plan achieves its purpose depends on specific facts, drafting, funding, timing, and administration.
The law changes; no duty to update
This article reflects statutes, regulations, and published sources known to us as of September 16, 2026. Tax and estate law change frequently. We have no obligation to update this article, and information that was accurate when written may later become inaccurate.
Third-party sources and links
Survey figures and other third-party information are summarized from the public sources listed above. We do not control, endorse, or guarantee the accuracy, completeness, or availability of any third-party content or link.
Examples are simplified
Examples, tables, and figures are simplified illustrations only. They are not projections or promises of any tax savings or result, and your circumstances will differ.
Jurisdiction
Our attorneys are admitted to practice before the Supreme Court of Arizona, the United States Tax Court, and the United States District Court for the District of Arizona. Discussion of other states' laws is general in nature; consult counsel licensed in that state. This article is not intended to solicit clients in any jurisdiction where doing so would not comply with applicable rules.
Limitation of liability
To the fullest extent permitted by law, Boland Law Group, PLLC and its attorneys and staff disclaim all liability for any loss, damage, tax, interest, penalty, or expense arising from any use of, or reliance on, this article or any linked content. Your use of this website is also subject to our Privacy Policy.
Attorney advertising
This article may be considered attorney advertising under applicable rules of professional conduct. Responsible attorney: Grant M. Boland, J.D., LL.M., Boland Law Group, PLLC, 15100 N. 78th Way, Suite 203, Scottsdale, Arizona 85260, (480) 420-8268.
Passionately Preserving Wealth™
Two generations of LL.M. counsel. Founder licensed in 1974.